UPI 0.4% Merchant Fee Delayed Until After Diwali: What You Pay, What Stays Free and What NRIs Need to Know
The planned 0.4% MDR on certain UPI merchant payments will not start on October 15. Here is what remains free, who may eventually pay the merchant-side charge, how the ₹300 cap works and what NRIs should know.
No, ordinary UPI users will not suddenly have to pay an extra transaction fee from October 15 — and the new merchant-side MDR that had been scheduled for that date has now been postponed until after Diwali.
The National Payments Corporation of India has deferred the implementation of the new Merchant Discount Rate, or MDR, on specified higher-value UPI merchant transactions. It had originally been due to take effect on October 15, 2026, but NPCI said the implementation would instead happen after the festive period on a date to be notified separately.
That distinction matters because two different questions have become mixed together in public discussion.
The first is whether consumers will be charged simply for using UPI. Under the framework announced by the government and NPCI, the answer is no.
The second is whether all UPI transactions will remain cost-free within the payment ecosystem. The answer to that is also more nuanced: once the deferred MDR framework eventually takes effect, specified person-to-merchant transactions above ₹2,000 will attract a merchant-side charge, subject to exemptions, reduced rates for certain sectors and a ₹300 cap.
For now, however, the planned October 15 start date is no longer in force. NPCI has said a new implementation date will be notified separately after Diwali.
Key Takeaways
October 15 MDR rollout postponed by NPCI until after Diwali.
Recommended Reading
Related Stories & In-Depth Guides
Curated editorial perspectives matching this topic.
The Supreme Court did not ban protests at Jantar Mantar on October 9. It asked authorities to consider a better venue. Two days later, Delhi Police formally de-notified Jantar Mantar and designated Ramlila Ground, Burari Ground and CBD Ground as Delhi’s new protest venues.
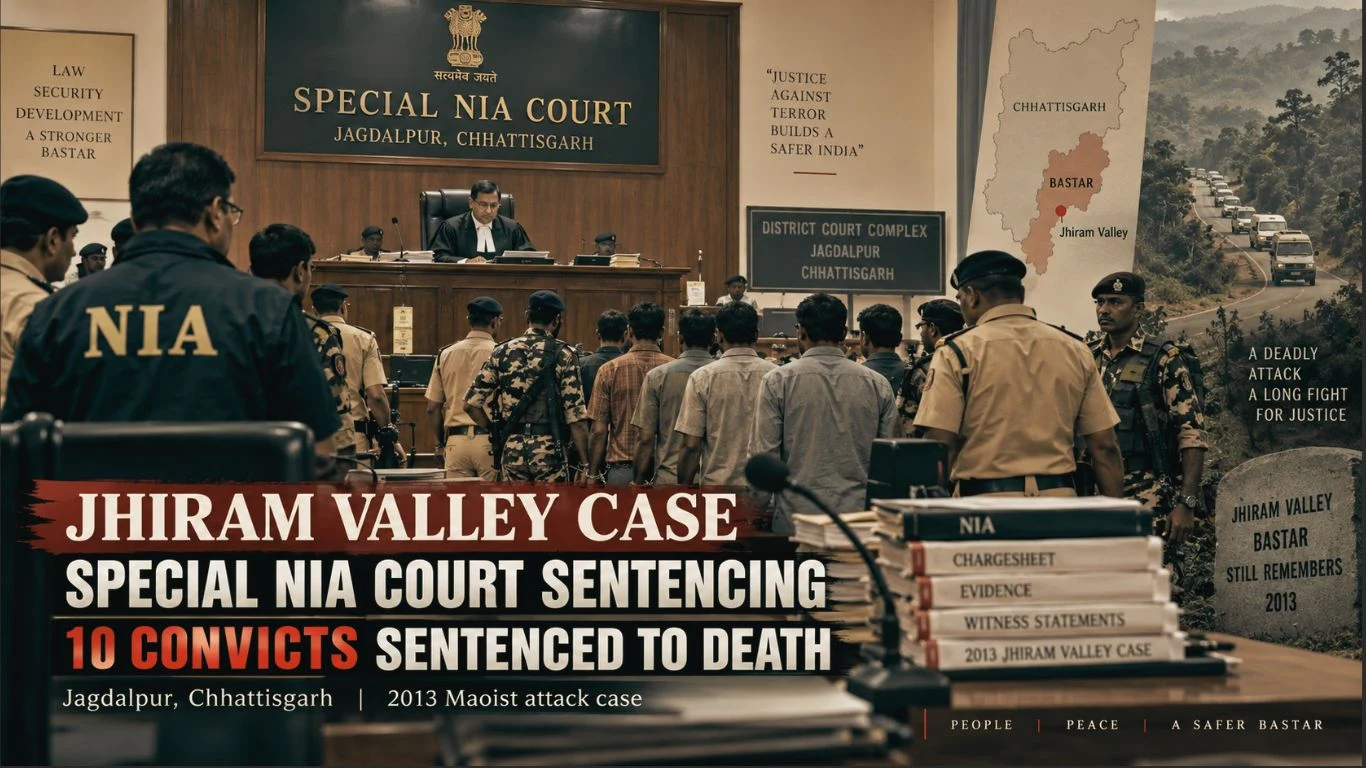
The Jagdalpur court imposed capital punishment on all 10 people convicted in the 2013 Maoist ambush on a Congress convoy in Chhattisgarh. Two women are among those sentenced. The death sentences must still go through the High Court confirmation process, and the defence can appeal.
Customers do not pay the 0.4% MDR.
Person-to-person transfers remain free regardless of amount.
Standard 0.4% applies only to eligible merchant payments above ₹2,000 (capped at ₹300).
New date yet to be notified; Supreme Court challenge ongoing.
What changed at the last minute?
The framework announced in September had set October 15, 2026 as the effective date for a new 0.4% MDR on specified person-to-merchant UPI payments above ₹2,000.
On October 13, NPCI postponed that rollout, citing the festive season. The revised implementation date has not yet been announced.
That means a shopper making an eligible merchant UPI payment on October 15 should not interpret older reports about the original deadline as meaning that the new MDR has automatically come into force.
The postponement changes the timing, not necessarily the underlying structure of the framework.
Unless NPCI or the government subsequently modifies the rules themselves, the framework announced in September remains the important guide to how the system is intended to operate once a new effective date is notified.
Will you pay extra for using UPI?
For an individual customer, the official framework says no.
The Ministry of Finance said the MDR is a charge within the merchant-payment ecosystem and is not a charge imposed on a customer simply for making a UPI payment.
Person-to-person transfers — such as sending money to a family member, friend or another individual — remain outside the MDR framework irrespective of the amount transferred.
The government also said UPI application providers cannot impose platform fees or hidden transaction charges on individuals under this framework, while banks have been advised to ensure that merchants do not pass the MDR on to customers.
This is why describing the measure simply as a “0.4% UPI charge for users” can be misleading.
It is a merchant discount rate, and its application depends on the type of transaction, merchant classification, transaction value and, in some sectors, a special rate.
How the proposed 0.4% MDR works
Under the announced framework, the standard MDR would apply to specified person-to-merchant, or P2M, UPI payments above ₹2,000.
The standard rate is 0.4% of the transaction value.
For transactions of ₹75,000 or more, the MDR is capped at ₹300 per transaction.
The money is not described by the government as a tax and is not collected as government revenue or retained by NPCI. The Ministry of Finance says it is distributed among participants in the payments ecosystem, including banks, payment service providers and UPI application providers.
But these rates should now be understood as the framework scheduled for implementation after the postponement, rather than as charges beginning on October 15.
₹500, ₹3,000 and ₹80,000: what would happen?
The simplest way to understand the framework is through examples.
UPI payment
Customer's MDR
Standard merchant MDR after implementation*
Explanation
₹500
₹0
₹0
Merchant payments up to ₹2,000 remain zero-MDR
₹3,000
₹0
₹12
0.4% of ₹3,000, if the payment and merchant fall under the standard MDR category
₹80,000
₹0
₹300
0.4% would be ₹320, but the standard MDR is capped at ₹300 for payments of ₹75,000 and above
*These examples assume a standard eligible P2M merchant transaction after the deferred framework actually takes effect. Small-merchant exemptions and special merchant categories can produce a different result.
The important point is that the amounts in the third column are merchant-side payment-processing costs under the framework — not an additional amount that the customer is supposed to be charged at checkout.
What remains completely free?
Several important categories remain outside the standard MDR.
Person-to-person transfers
Sending money from one individual to another remains free under the new framework regardless of the amount transferred.
That means paying a friend back, transferring money to a relative or carrying out another genuine P2P transfer is not covered by the new merchant MDR.
Merchant payments of ₹2,000 or less
P2M transactions up to ₹2,000 remain at zero MDR.
The government says that when the small-merchant exemption is also taken into account, roughly 96% of merchant transactions are expected to remain unaffected by the new MDR framework.
Eligible small merchants
The framework also protects small merchants classified under the applicable P2PM arrangement.
The Ministry of Finance said small merchants, including street vendors, receiving up to ₹1 lakh per month through UPI QR codes under that category would continue to have zero MDR on their transactions.
That exemption is significant because a transaction above ₹2,000 does not, by itself, tell you that a merchant will necessarily pay the standard 0.4%.
The merchant's category also matters.
Some sectors do not use the standard 0.4% rate
Another reason the “0.4% on every UPI payment above ₹2,000” description is inaccurate is that the framework establishes special treatment for some sectors.
For transactions above ₹2,000 in specified essential or thin-margin sectors, including railways, telecommunications, insurance, fuel and agricultural inputs, the announced MDR is a flat ₹5 per transaction rather than the standard 0.4%.
Payments relating to mutual funds, securities, stockbrokers and dealers have a separate 0.02% rate, capped at ₹300 per transaction.
Consumers therefore should not try to calculate the merchant's cost merely by multiplying every payment above ₹2,000 by 0.4%.
Why introduce MDR at all?
India's zero-MDR approach helped UPI develop into the country's dominant retail digital-payment system, but payment processing still has costs.
Banks, payment-service providers and UPI applications have to maintain technology infrastructure, transaction processing, cybersecurity, fraud controls, customer support and system capacity.
The government's stated rationale is that a limited merchant-side revenue model for higher-value payments can help support the continuing operation and expansion of the system while shielding individuals and small businesses from charges.
The Ministry of Finance has also said that an amount equivalent to 5% of total MDR collections is intended to go into a dedicated fund supporting wider UPI adoption among small merchants.
That policy argument is distinct from whether the precise legal mechanism used to introduce the MDR is valid — which is one of the questions now before the Supreme Court.
What the Supreme Court actually asked
The UPI MDR framework is facing a legal challenge in the Supreme Court.
In a hearing on September 28, 2026, the court declined to immediately stay the framework but asked the Centre, RBI and NPCI to respond to the challenge.
The bench questioned the legal character and basis of the MDR, including how the charge is authorised and who receives the money. The Centre's position before the court was that the MDR was not a tax collected by the government but a settlement-related charge within the payment system.
The court did not declare the MDR illegal, nor did it finally uphold its legality at that stage. It sought responses before examining the challenge further. Reports of the hearing said the respondents were given four weeks to file their counter-affidavits.
It is also important not to confuse the Supreme Court proceedings with NPCI's subsequent postponement.
NPCI's October 13 announcement attributed the delay to the festive season. There is no verified basis at this stage to say that the Supreme Court ordered the October 15 rollout to be postponed.
A short timeline
September 14: The Centre issued the notification forming part of the new framework for UPI MDR treatment.
September 15: The government detailed the structure: P2P transfers remain free, eligible merchant payments above ₹2,000 can attract MDR, and about 96% of merchant transactions are expected to remain unaffected.
September 28: The Supreme Court refused an interim stay but sought explanations from the Centre, RBI and NPCI regarding the legal basis and operation of the MDR framework.
October 13: NPCI postponed the October 15 implementation until after Diwali and said a new date would be separately notified.
Can a shop add 0.4% to your bill?
The government's framework does not treat MDR as a consumer surcharge.
The Ministry of Finance has said banks were advised to ensure merchants do not pass the MDR on to customers.
So if the standard MDR eventually becomes applicable to a merchant, that does not mean the official framework authorises the merchant to automatically add 0.4% to a customer's UPI bill.
There is an important practical distinction here.
A merchant bearing higher operating costs and changing the general price of a product over time is different from explicitly adding an unauthorised “UPI fee” to a customer's bill. Consumers should therefore look carefully at checkout amounts rather than assuming that any new UPI surcharge is part of the official consumer-facing framework.
What does this mean for NRIs?
For NRIs, it helps to separate three different issues: whether an NRI can register for UPI, whether UPI can be used at an overseas merchant, and whether the new Indian merchant MDR creates a consumer fee.
NRIs can use UPI with supported international numbers
NPCI has extended UPI access to NRIs holding eligible NRE or NRO accounts.
An NRI can link an international mobile number to the relevant bank account and use a UPI-powered application that supports international-number onboarding, subject to the bank's conditions and NPCI's supported-country, bank and app arrangements.
Support is not universal across every country, bank or UPI app. NRIs should therefore verify the current NPCI-supported list and their own bank's eligibility rather than assuming that any foreign mobile number will work.
Using UPI abroad is a separate feature
NPCI's UPI Global or UPI International facility allows eligible users to make QR-based payments from Indian bank accounts at selected overseas merchant locations where the service is supported.
The user must have the international-payment feature activated where required, the overseas merchant must support the relevant UPI acceptance network, and the payment screen should show details such as the foreign-currency amount, Indian-currency amount and applicable exchange rate or fees before authorisation.
That is separate from the domestic discussion over the new standard 0.4% MDR.
The official material reviewed for this article does not establish that an NRI using UPI at an overseas merchant will personally be charged 0.4% because of the new MDR framework. It would therefore be inaccurate to extend the domestic merchant-rate headline automatically to every overseas UPI transaction.
NRIs should instead check the specific exchange rate, foreign-payment terms and any fees displayed by their bank or supported UPI service when making an international payment.
Sending money through UPI is not suddenly chargeable because you are an NRI
The basic distinction remains between the type of transaction and the merchant framework.
The announced MDR does not create a general consumer charge merely because the person using UPI is an NRI or because their account is an NRE or NRO account.
Eligibility, foreign-exchange rules and international acceptance can differ, but those issues should not be confused with the domestic 0.4% merchant MDR.
What should ordinary UPI users do now?
For most people, there is nothing they need to change on October 15.
You can continue using UPI for person-to-person transfers and merchant purchases in the normal way.
There is no need to split a genuine P2P transfer simply to avoid the ₹2,000 threshold, because P2P payments are already outside the MDR framework irrespective of value.
Similarly, consumers should not assume that every merchant payment above ₹2,000 will eventually cost the merchant exactly 0.4%. Small-merchant exemptions, category-specific rates and the ₹300 cap can all change the calculation.
Most importantly, the October 15 date that appeared in earlier announcements and news reports is no longer the implementation date.
What happens next?
The immediate development to watch is NPCI's revised implementation notice.
NPCI has said the MDR will be implemented after Diwali, but as of October 14 it has not announced the replacement date.
A second track is the Supreme Court case. The court has asked for responses on the legal basis and mechanics of the framework, but has not delivered a final ruling on the challenge.
There is therefore a difference between the rules that have been announced, the date on which they will begin operating, and the legal challenge still being considered by the court.
For consumers, however, the most important point is straightforward:
UPI does not become a paid service for ordinary users on October 15. The proposed MDR is a merchant-side charge for specified transactions, and even that rollout has now been deferred until after Diwali.
Key Takeaway
UPI 0.4% MDR delayed until after Diwali. Customers do not pay.
P2P transfers and payments ≤ ₹2,000 remain free. New date yet to be notified.
The Rajatheertha Team publishes news, explainers, guides and updates across India and the world. Our coverage follows Rajatheertha's editorial, verification and corrections standards.
Entry and exit are restricted at six central Delhi Metro stations until 4 PM as the INDIA bloc prepares to march towards the Supreme Court. Delhi Traffic Police has also identified 30 locations where diversions may be imposed from 6 AM depending on conditions on the ground.
Delhi has ordered retail liquor shops to remain closed on October 9 and 10, 2026, as a preventive public-order measure based on Delhi Police inputs. Here is why the shops are shut, which outlets are affected and what remains open.
The Supreme Court has reaffirmed that arrested persons must receive the grounds of arrest in writing and in a language they understand, holding that Article 22(1) applies across criminal laws, including special statutes such as PMLA and UAPA.
The Home Ministry has formally added the Shahzad Bhatti Network to the First Schedule of the UAPA, citing alleged cross-border arms, explosives and narcotics smuggling, recruitment of local criminals and the use of digital platforms for terror-related activity. The designation follows a multi-state
Central Government employees and pensioners are scheduled to receive September 2026 salary, wages and pension in advance on Friday, September 25, ahead of the proposed September 28–30 bank strike. Here is who is covered and what the order means.
Pope Leo XIV is walking, eating normally and has celebrated Mass at Rome’s Gemelli Hospital as the Vatican reports an expected recovery after surgery for lung adenocarcinoma. Important questions about staging, further treatment and his November travel plans remain unresolved.






0 Comments