India Inflation Hits 5.54%: Will RBI Hike Again? What It Means for Your EMI
India’s retail inflation rose to 5.54% in September, just days after the RBI increased the repo rate to 5.50%. Here is what the inflation surge means for another possible rate hike, home-loan EMIs and household budgets.
Editorial illustration of India inflation, RBI rate decision and home-loan EMI impact
Table of Contents (17 sections)
Your home-loan EMI could rise, but not automatically: borrowers with floating-rate loans may face higher interest costs if their lender passes through the Reserve Bank of India’s latest rate increase, while fixed-rate borrowers generally will not see an immediate change during their fixed-rate period.
That question has become more important after India’s retail inflation accelerated sharply to 5.54% in September 2026, putting inflation much closer to the upper end of the Reserve Bank of India’s tolerance range and strengthening expectations that monetary policy may have to remain tight.
The Ministry of Statistics and Programme Implementation said the Consumer Price Index-based inflation rate increased from 4.83% in August to 5.54% in September.
Food prices were an even bigger source of pressure. Consumer food inflation jumped from 5.97% in August to 7.74% in September.
The inflation figures arrived only five days after the RBI’s Monetary Policy Committee raised the policy repo rate by 25 basis points on October 7, taking it from 5.25% to 5.50%.
It was the RBI’s first repo-rate increase in nearly four years.
Recommended Reading
Related Stories & In-Depth Guides
Curated editorial perspectives matching this topic.
Iran’s economy contracted by 10.1% year-on-year during the first quarter of its current Persian calendar year, according to official data, with a collapse in oil and natural-gas activity driving much of the decline. The figures cover the first months of the US-Israel conflict with Iran, although the
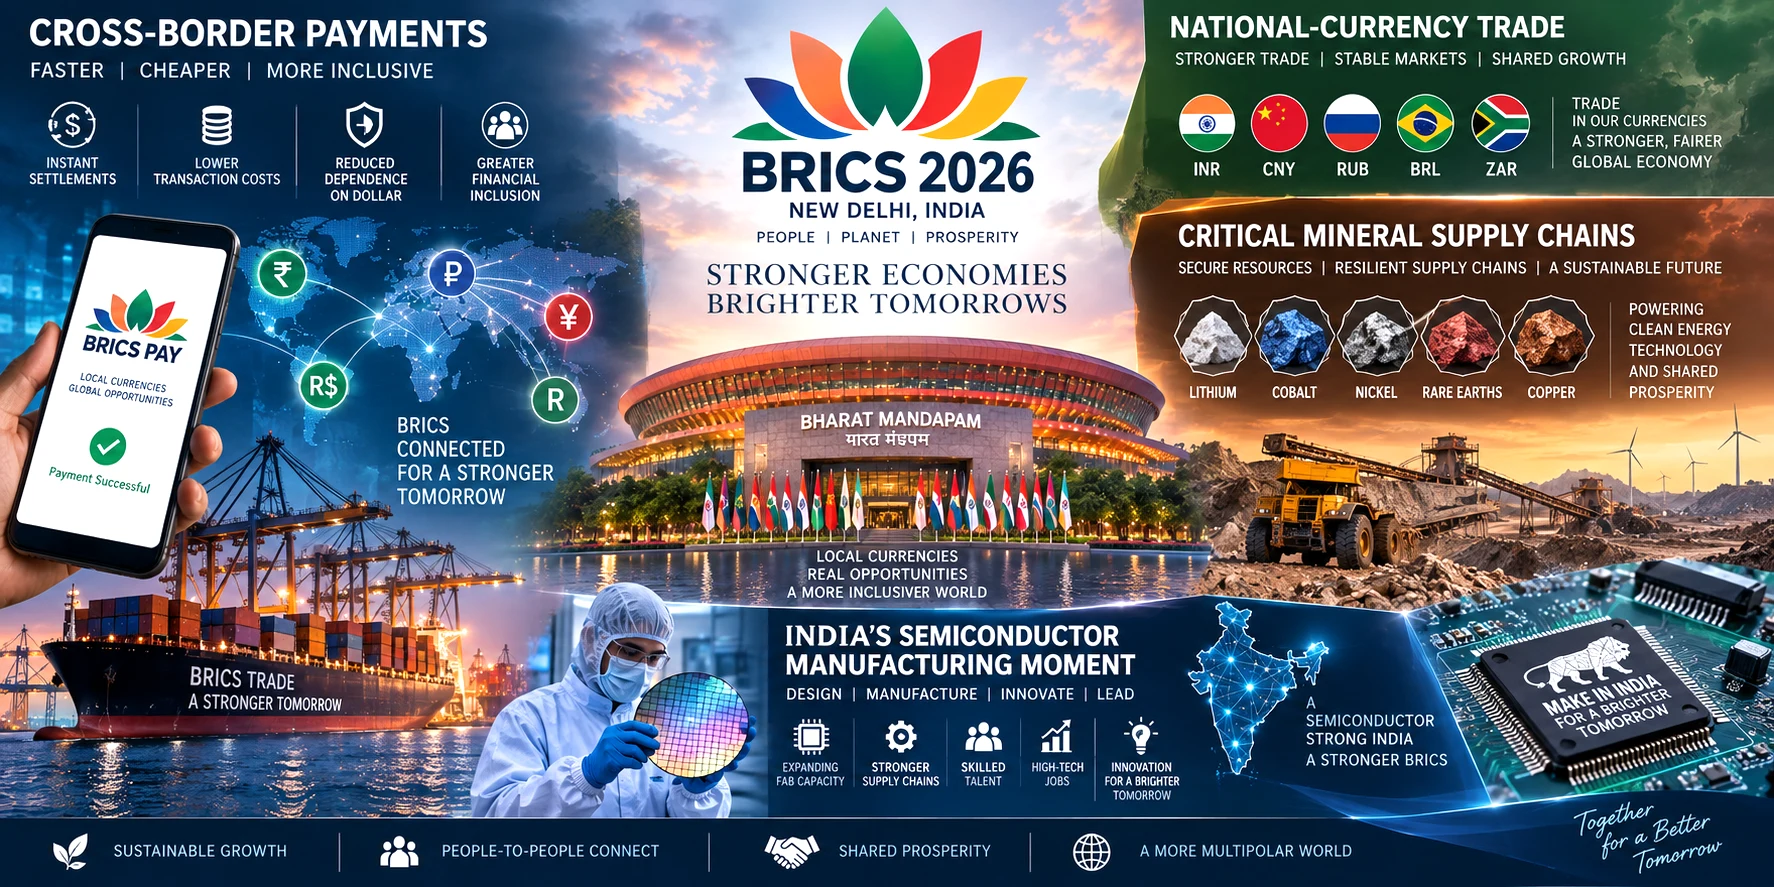
The New Delhi Declaration backs more interoperable payment systems and voluntary use of national currencies while calling for diversified critical-mineral supply chains, as India’s expanding semiconductor ecosystem highlights the commercial stakes behind the resilience agenda.
The sequence is important for borrowers.
The RBI had already decided that inflation risks were serious enough to justify higher interest rates before it had the September CPI number. The subsequent 5.54% reading gives policymakers another reason to watch prices closely ahead of the next monetary-policy meeting in December.
But another rate increase is not yet guaranteed.
The RBI will have additional information before making that decision, including October inflation, food prices after fresh crop arrivals, crude-oil developments, the rupee, domestic growth and the transmission of the October rate increase through the banking system.
Key Takeaways
September retail inflation: 5.54% (up from 4.83% in August).
Food inflation: 7.74% (up from 5.97%).
RBI raised repo rate to 5.50% on Oct 7; stance shifted to “calibrated tightening”.
Next MPC meeting: December 2–4; October CPI due Nov 12.
Floating-rate home loans may see higher EMIs; fixed-rate loans generally protected during fixed period.
India’s Inflation Jump: The Key Numbers
MoSPI’s September 2026 data show a clear acceleration in price pressures.
Headline CPI inflation: 5.54%
August headline inflation: 4.83%
Food inflation: 7.74%
August food inflation: 5.97%
Rural inflation: 6.08%
Urban inflation: 4.88%
The September CPI number remains within the RBI’s inflation tolerance band of 2% to 6%, but it is significantly above the central bank’s 4% medium-term target.
That distinction matters.
Crossing 4% does not automatically force the RBI to raise interest rates. The inflation-targeting framework allows inflation to fluctuate within the wider tolerance band.
However, a sustained period substantially above 4%, especially when accompanied by broadening price pressures, can increase the case for monetary tightening.
At 5.54%, inflation is also only 0.46 percentage point below the 6% upper tolerance threshold.
Why Did Inflation Rise So Sharply?
Food was one of the clearest drivers.
India’s Consumer Food Price Index recorded 7.74% year-on-year inflation in September, compared with 5.97% in August.
Some individual items registered exceptionally large increases.
According to the official CPI release, onion inflation reached 108.09% year-on-year in September. Ginger inflation was 62.85%, garlic 54.62% and lemon 36.41%.
That does not mean every household’s grocery bill rose by those percentages. CPI measures price movements across a weighted basket, and individual households consume different combinations and quantities of products.
The figures nevertheless show why food inflation has become a significant concern for household budgets.
At the same time, inflation was not identical across the country.
Rural headline inflation stood at 6.08%, compared with 4.88% in urban India.
Food inflation was also higher in rural areas at 8.06%, compared with 7.18% in urban areas.
That gap can matter because food generally represents a larger share of spending for lower-income households.
Food vs Fuel: Where Is the Pressure Coming From?
Food
Food inflation: 7.74%
Food and beverages division: 7.36%
Onion inflation: 108.09%
Ginger inflation: 62.85%
Garlic inflation: 54.62%
Energy and transport-related components
Electricity, gas and other fuels: 3.24%
Transport: 5.01%
Operation of personal transport equipment: 7.46%
The numbers show that September’s inflation problem was not simply a fuel story.
Food prices were rising substantially faster than the broad electricity, gas and other fuels category.
But transport-related inflation remained elevated, and global crude-oil prices continue to matter because India imports a large share of its crude requirements.
Higher international energy costs can affect inflation through several channels even when retail petrol or diesel prices do not immediately move by the same amount.
They can raise freight costs, aviation expenses, manufacturing costs and the cost of transporting food and other goods across the country.
That is one reason policymakers watch both food and energy developments rather than reacting to the headline CPI number alone.
What Did the RBI Do on October 7?
The RBI Monetary Policy Committee increased the policy repo rate by 25 basis points from 5.25% to 5.50% on October 7.
The six-member committee voted unanimously for the increase.
The RBI also changed its monetary-policy stance from “neutral” to “calibrated tightening”.
The wording matters because it signals a less accommodative policy environment.
It does not promise another hike at the next meeting.
It does, however, indicate that the central bank is prepared to keep monetary conditions restrictive if inflation risks remain elevated.
The October increase came after inflation had already been running above the RBI’s 4% target and amid concerns involving food prices, global energy costs and financial-market conditions.
September’s 5.54% inflation figure was published after that decision.
Will the RBI Raise the Repo Rate Again?
Another increase is now a meaningful possibility, but it should not be presented as certain.
The next scheduled Monetary Policy Committee meeting runs from December 2 to December 4, 2026.
Before then, the RBI will receive the October CPI reading, which MoSPI is scheduled to release on November 12.
That report could become one of the most important pieces of data for the December decision.
If inflation remains close to 6%, food prices stay elevated, energy costs remain high and price pressures spread more widely through the economy, the case for another hike would strengthen.
If inflation begins easing materially, food supply improves and financial conditions stabilise, the MPC could instead choose to pause and observe the effect of the October increase.
There is also growing discussion about the size of any possible next move.
Reuters reported on October 16, citing sources familiar with the central bank’s thinking, that a 50-basis-point increase could be discussed at the December review if inflation conditions justify front-loading rate increases.
HSBC and State Bank of India have also been reported as expecting a 50-basis-point December increase.
Those are forecasts and discussions, not an announced RBI decision.
The distinction is important for borrowers: people should not restructure loans today on the assumption that the repo rate will definitely rise to 6%.
What Does 5.54% Inflation Mean for Your EMI?
Inflation does not directly change your EMI.
The chain is:
Higher and persistent inflation
→ greater pressure on RBI to tighten monetary policy
→ higher repo rate
→ possible increase in benchmark-linked lending rates
→ higher borrowing cost for affected floating-rate loans.
That final step depends on the individual loan.
Many newer floating-rate retail loans are linked to external benchmarks, including the RBI repo rate.
When the benchmark rises, the applicable loan interest rate may eventually rise according to the lender’s reset rules.
Banks and housing-finance companies can also differ in how they adjust the EMI or loan tenure.
Some borrowers may see a higher monthly EMI.
Others may initially see the repayment tenure extended.
In some situations, lenders may offer borrowers a choice between a higher EMI, a longer tenure or partial prepayment.
Borrowers should therefore check their own sanction letter, benchmark, spread and reset date rather than assuming every home loan will move identically.
EMI Example: ₹30 Lakh and ₹50 Lakh Home Loans
The following calculation is an illustration, not a quotation from any lender.
Assumptions:
Remaining loan tenure: 20 years
Starting interest rate: 8.50%
Scenario 1: Rate increases by 25 basis points to 8.75%
Scenario 2: Rate increases by a cumulative 50 basis points to 9.00%
Loan Amount
EMI at 8.50%
EMI at 8.75%
Increase After 25 bps
EMI at 9.00%
Increase After 50 bps
₹30 lakh
₹26,035
₹26,511
about ₹477
₹26,992
about ₹957
₹50 lakh
₹43,391
₹44,186
about ₹794
₹44,986
about ₹1,595
These figures illustrate how a relatively small change in interest rates can accumulate into a meaningful monthly expense on a large, long-term loan.
Actual EMIs will differ depending on the borrower’s outstanding principal, remaining tenure, interest rate, benchmark, spread and lender policy.
Does the October RBI Hike Mean Your EMI Has Already Increased?
Not necessarily.
A repo-rate increase is a monetary-policy decision, not an instruction that every bank must increase every borrower’s EMI by exactly the same amount on the same day.
The effect depends on how the loan is priced.
A repo-linked floating-rate borrower could experience relatively quick transmission after the applicable reset.
A borrower under another floating benchmark could see a different timing or magnitude.
A fixed-rate borrower generally remains protected from immediate changes for the duration of the fixed-rate arrangement, subject to the terms of the loan contract.
This is why borrowers should check the “benchmark” and “reset frequency” fields in their loan documents.
Why the Next Rate Decision Is More Complicated Than Inflation Alone
Central banks do not make monetary-policy decisions from one inflation number.
The RBI has to balance price stability against economic activity and financial stability.
India’s economy grew 7.8% year-on-year in the April-June quarter of FY2026-27, giving policymakers some room to address inflation without immediately confronting a weak-growth environment.
But aggressively increasing interest rates also has costs.
Higher rates can reduce new housing demand, make vehicle and business loans more expensive, increase corporate financing costs and reduce discretionary spending.
The RBI therefore has to judge whether inflation is temporary and supply-driven or becoming more persistent across the economy.
A temporary vegetable-price shock may not require the same monetary response as sustained price increases spreading across goods and services.
The Rupee Is Another Factor to Watch
Inflation is not the only pressure facing monetary policy.
The rupee has also experienced significant volatility during 2026 as India dealt with capital outflows, high global energy prices and changing international interest-rate conditions.
Higher domestic interest rates can sometimes help support a currency by improving the relative return available on rupee assets.
But using interest rates aggressively for currency management can impose additional costs on domestic borrowers and businesses.
The RBI therefore has to balance inflation control, currency stability and economic growth rather than targeting any one variable in isolation.
What Borrowers Should Watch Before December
Home-loan borrowers do not need to predict the exact outcome of the next RBI meeting.
They can instead monitor a small number of indicators.
First is the October CPI release on November 12.
If headline inflation rises closer to or above 6%, expectations of further tightening could increase.
Second is food inflation.
A meaningful cooling in vegetable, cereal and other food prices could reduce some of the pressure visible in September.
Third is crude oil.
India remains sensitive to global energy prices, particularly when geopolitical tensions affect supplies and shipping.
Fourth is the rupee.
Continued currency weakness can add to imported inflation risks.
Fifth is bank lending-rate transmission.
Borrowers should watch whether their lender changes the benchmark rate applicable to their loan after the October repo-rate increase.
Should You Prepay Your Home Loan Now?
A single inflation report is not, by itself, a reason for every borrower to make a large prepayment.
Prepayment decisions depend on personal circumstances.
A borrower with surplus cash, an adequate emergency fund and a high floating-rate loan may find partial prepayment useful because it reduces the outstanding principal on which future interest is calculated.
But using all available savings to reduce a home loan can create another problem if it leaves the household without sufficient emergency liquidity.
Borrowers should also compare the effective loan cost with alternative uses of the money and consider tax implications where relevant.
The more immediate step is simpler: check the loan benchmark, current interest rate, reset date and outstanding tenure.
What About Fixed Deposits?
Higher policy rates are generally negative for borrowers but can eventually create opportunities for depositors.
Banks may raise some fixed-deposit rates if their funding requirements and competitive conditions justify it.
But deposit rates do not mechanically increase by the exact amount of an RBI repo-rate hike.
Banks set deposit pricing based on liquidity, funding needs, maturity profile and competition.
Therefore, depositors should compare actual published rates rather than assuming a 25-basis-point repo increase means every FD will soon pay 0.25 percentage point more.
Why September Inflation Matters More Than the Headline Number Alone
The biggest concern is not simply that inflation reached 5.54%.
It is the combination of developments.
Inflation has moved materially above the RBI’s 4% target.
Food inflation has accelerated to 7.74%.
Rural inflation has crossed 6%.
The RBI has already started raising rates.
The central bank has shifted to a calibrated-tightening stance.
Global energy and currency risks remain relevant.
Together, those factors leave borrowers facing a more uncertain interest-rate environment than they did only a few months ago.
What Happens Next?
The next major inflation checkpoint is November 12, when MoSPI is scheduled to release CPI data for October.
The RBI’s Monetary Policy Committee will then meet from December 2 to December 4.
Between now and then, policymakers will assess inflation, food supplies, oil prices, the rupee, financial conditions and economic growth.
Another repo-rate increase is therefore a real possibility.
A 25-basis-point move is not the only scenario being discussed in financial markets; a larger 50-basis-point increase has also entered the debate.
But neither outcome is predetermined.
For borrowers, the most practical conclusion is not that every EMI will definitely rise.
It is that the probability of borrowing costs remaining elevated — and potentially increasing further for some floating-rate loans — has grown after September inflation reached 5.54%.
Anyone with a floating-rate home loan should now check the benchmark and reset terms of the loan, calculate how a further 25- or 50-basis-point increase would affect the household budget, and watch the November inflation data before the RBI’s December policy decision.
Key Takeaway
India inflation at 5.54%; RBI already hiked to 5.50%.
Another rate increase possible in December — floating-rate EMIs may rise.
The Rajatheertha Team publishes news, explainers, guides and updates across India and the world. Our coverage follows Rajatheertha's editorial, verification and corrections standards.
Finance Minister Nirmala Sitharaman says India cannot abruptly abandon Russian crude and will base oil purchases on availability, price and refinery suitability as a new US law raises the risk of tariffs of up to 100% on major Russian-energy buyers.
The Bank of Japan has raised its benchmark interest rate to 1.25%, taking borrowing costs to their highest level in 31 years as policymakers step up efforts to prevent inflation from moving persistently above the central bank’s target.
India received a record $94.53 billion in total FDI in FY2025-26, up about 17% from the previous year. Singapore led equity investment, software and hardware was the top sector, while Maharashtra attracted the most FDI equity.
Sensex and Nifty rebounded on September 25 after Thursday's sharp selloff. At 2:35 PM IST, Sensex was up 328 points at 73,908 while Nifty gained 68 points to 23,131, helped by value buying and softer crude.
The RBI has raised the repo rate by 25 basis points to 5.50%, its first hike since February 2023. Here's what the October 2026 decision could mean for home loan EMIs, loan tenures, fixed deposits and new borrowers.
Days after raising the repo rate to 5.50%, the RBI has tightened banks’ daily liquidity rules and announced a ₹25,000 crore bond sale. Here is what the measures mean—and do not mean—for home-loan borrowers and FD savers.



0 Comments